By the Cemex Ventures Investment Team
Capital is not just back in ConTech. It is accelerating. Q3 2026 closed with $7.541B invested across 92 transactions, a 303% increase in invested capital and a 20% increase in deal count compared with Q3 2025. It is, by a wide margin, the strongest quarter we have tracked this year.
Headline figures, however, only tell part of the story. Autodesk’s $3.6B acquisition of MaintainX accounts for almost half of the quarter’s volume on its own. That is why, as we do every quarter, our Investment Team has looked beneath the surface. Excluding that transaction, ConTech still attracted $3.941B across 91 deals, up 111% year-on-year. In other words, the underlying market more than doubled. To put that in perspective, Q3’s underlying volume alone exceeds the $2.884B deployed across the whole of H1 2026, as reported in our Q2 & H1 2026 analysis.
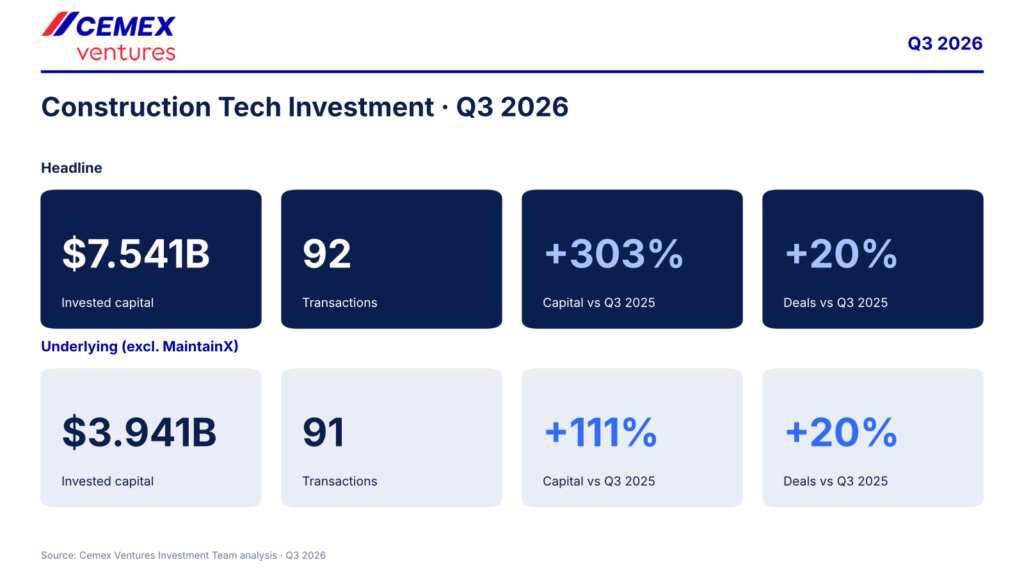
The rebound extends well beyond a single landmark transaction. With or without MaintainX, Q3 2026 shows a significantly more active investment environment: more deals than a year ago, and far more capital behind them.
Unless stated otherwise, all figures from this point onwards exclude the MaintainX acquisition, so that the analysis reflects the real dynamics of the ConTech market rather than one exceptional strategic move.
” The real story of Q3 is not the size of the biggest deals, but the breadth of activity beneath them. Capital more than doubled year-on-year even excluding MaintainX, indicating a healthier funding environment across the sector. While signs point a positive trend, higher interest rates and persistent inflation risks may temper investor enthusiasm in the coming quarters, reinforcing a flight toward quality and concentrating capital around the strongest teams, technologies, and business fundamentals ” — Miguel Carralón, Venture Investments & Partnerships at Cemex Ventures
Concentration at the Top: Mega-Deals Shape the Quarter Investment volume remained highly concentrated in a small number of very large transactions. MaintainX alone represented roughly 48% of headline Q3 capital. Two further deals amplified the quarter: Motive’s $1.3B growth financing and Procore’s $845M acquisition of DroneDeploy. Together, these two transactions account for more than half (54%) of the $3.941B underlying volume.
The rest of the top 10 confirms the appetite for proven category leaders and deep-tech bets alike: Mariana Minerals ($310M Series B), Gravis Robotics ($200M), Buildots ($130M), ICON (115𝑀), TerraFirma (100M), NavVis ($85M Series D) and P-1 AI ($50M). Excluding MaintainX, the remaining nine deals of the top 10 add up to $3.135B, close to 80% of underlying volume.
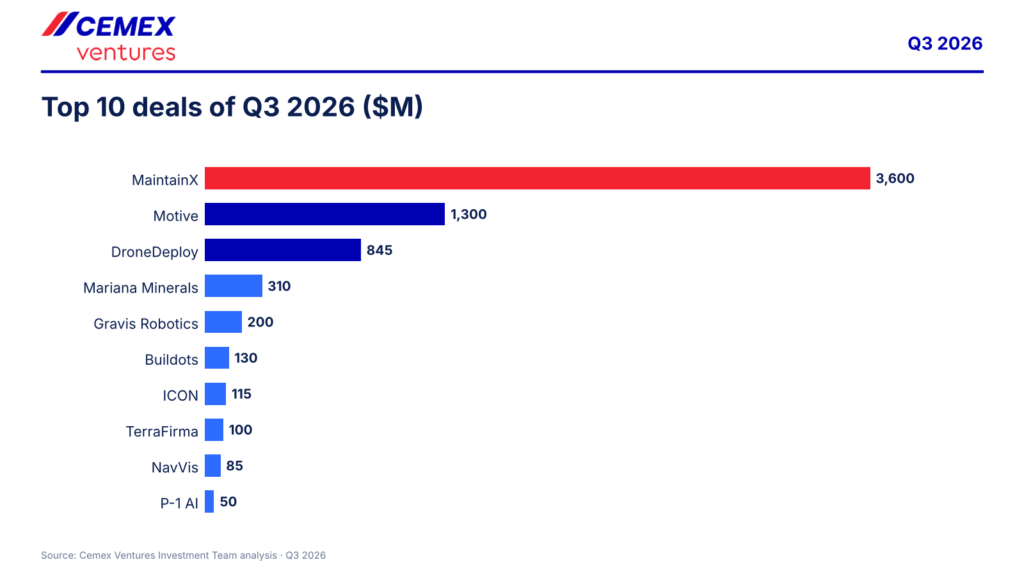
Capital is becoming increasingly concentrated around proven winners. Investors are willing to deploy substantial amounts of capital behind companies that combine strong growth, market adoption, scalable business models, and the potential to redefine established construction workflows and business models.
“Large rounds like these send a clear message to the ecosystem: when a construction technology company proves it can scale, there is now capital ready to back it at a size we simply did not see two or three years ago. The challenge for the rest of the market is that the bar to reach that stage has never been higher.” — Jose Antonio Brunet, Leader at Cemex Ventures
At Cemex Ventures, we analyze the market through our four focus areas: Green Construction, Supply Chain, Enhanced Productivity and Construction’s Future. In Q3, the picture changes significantly depending on whether we look at capital or at deal count.
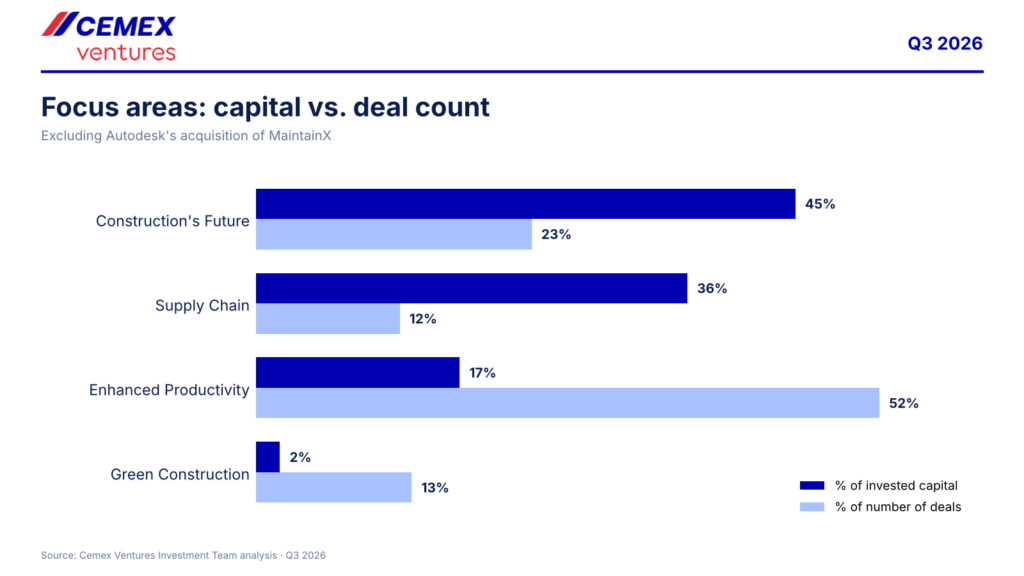
Construction’s Future was the largest destination for capital, attracting 45% of Q3 investment volume, while representing 23% of transactions. This is the area that brings together AI, robotics, autonomy, reality capture and advanced digital capabilities, the technologies that will define how construction is executed in the next decade. Rounds such as Gravis Robotics, Buildots, ICON and NavVis illustrate how investors are concentrating larger checks around companies connecting the digital and physical layers of construction.
Supply Chain captured 36% of invested capital with just 12% of deals, the highest capital-per-deal ratio of any focus area. Large transactions in fleet operations, materials and industrial logistics pushed this category well above its weight in deal count, confirming the trend we already highlighted in H1: supply chain digitization is no longer a niche, it is a strategic priority.
Enhanced Productivity represented 52% of all transactions, but only 17% of capital. Productivity solutions (project management, field execution, estimating, scheduling, document intelligence) continue to generate the broadest startup and investor activity, typically through smaller, earlier rounds. This is where much of the sector’s entrepreneurial energy sits, and where many of tomorrow’s category leaders are likely being funded today.
“The gap between deals and dollars in Enhanced Productivity is not a weakness, it is a pipeline. More than half of the quarter’s transactions are in this space, mostly at early stage. Many of these companies are solving very concrete problems on the jobsite, and the ones that build real defensibility around data and workflows will be the growth rounds we see in two or three years.” — Miguel Carralón, Venture Investments & Partnerships at Cemex Ventures
Green Construction attracted just 2% of capital, despite accounting for 13% of deals. Activity is there: founders keep building and investors keep backing them at early stage. But large checks remain elusive. Decarbonization technologies in construction often require longer validation cycles, heavier capital expenditure and, in many cases, a regulatory or pricing signal that makes adoption economically compelling.
“We see a lot of high-quality green construction startups, but most of them are still proving their technology at industrial scale, and that naturally keeps ticket sizes small. The inflection point will come when regulation and carbon pricing turn decarbonization from a ‘nice to have’ into a cost of doing business. When that happens, the capital will move quickly, and the companies already validated with industry partners will be best placed to capture it.” — Jose Antonio Brunet, Leader at Cemex Ventures
North America strengthened its dominance significantly, attracting 80% of invested capital and 46% of Q3 transactions. Europe represented only 13% of capital but 35% of deals, while Asia & Oceania accounted for 15% of transactions and just 3% of capital. The Middle East contributed 4% of capital and 3% of deals, and LATAM and Africa did not register disclosed activity this quarter.
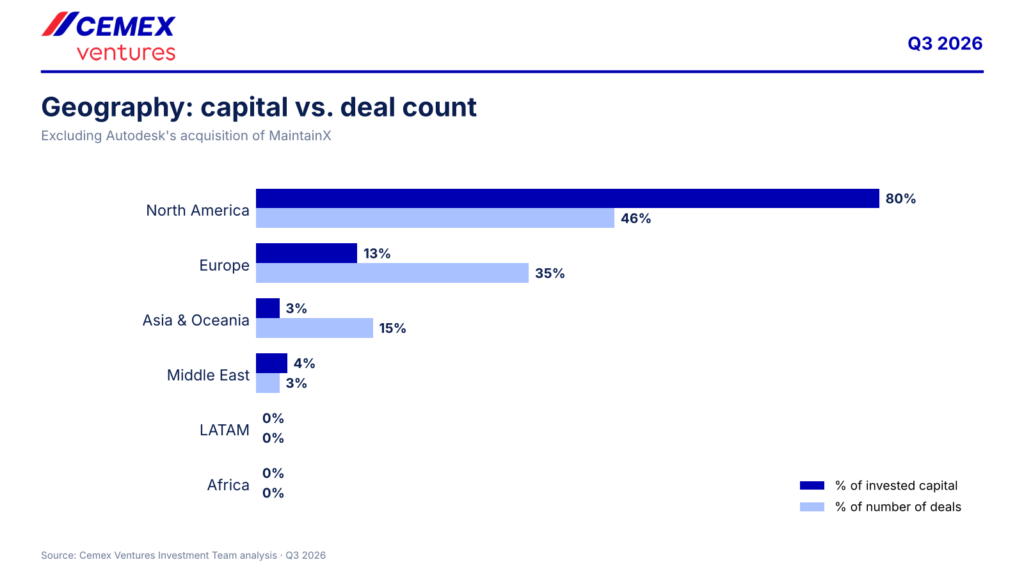
Translated into average ticket sizes, the contrast is striking. An average North American deal in Q3 was around $75M, compared with roughly $16M in Europe and below $10M in Asia & Oceania.
North America dominates capital deployment and large-scale funding, while Europe and APAC contribute a meaningful share of deal formation at much smaller ticket sizes. The gap is not about the quality of entrepreneurs. It reflects the depth of growth-stage capital available in each market and the size of the domestic construction and infrastructure opportunity.
“Europe is producing a third of the deals in ConTech, which says a lot about the quality of its founders. What it still lacks is the growth capital to keep its best companies scaling from Europe. That is precisely where corporate investors can make a difference, by combining capital with access to real projects, real customers and real data.” — Miguel Carralón, Venture Investments & Partnerships at Cemex Ventures
Early-stage investment remained the backbone of the ConTech market. Of the 91 transactions, 63 were completed between Pre-Seed and Series A, equivalent to 69% of total deal activity. Series B accounted for 10 transactions (11%), no Series C rounds were recorded, three deals were late stage (3%), six were M&A (7%) and nine fell into other categories (10%).
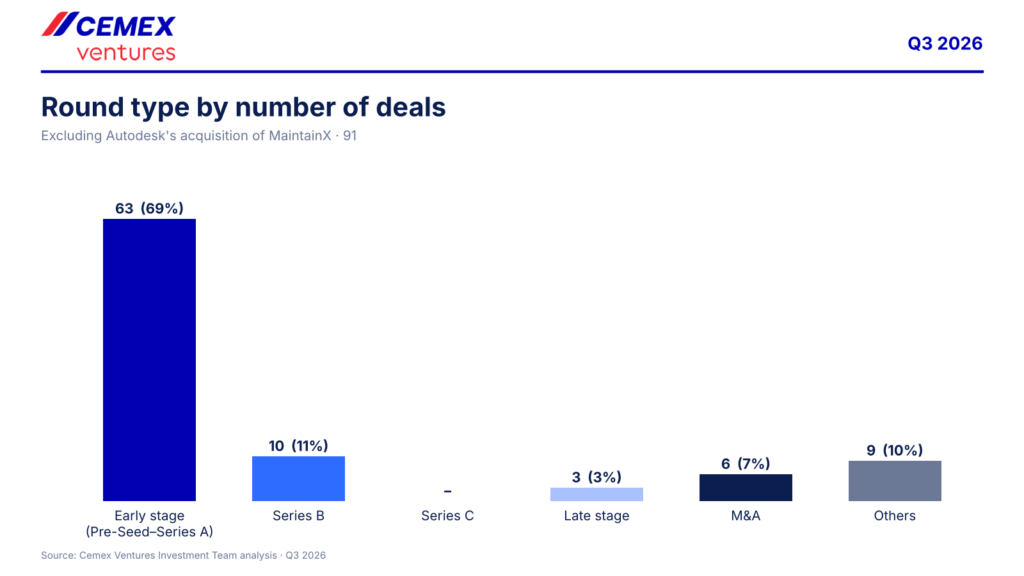
This combination of strong early-stage activity and a handful of very large transactions points to an increasingly barbell-shaped market. Investors continue to place numerous bets on emerging technologies, while concentrating larger amounts of capital in a relatively small group of proven category leaders. The middle of the curve, especially Series C, remains thin, and this is where the “Series B to growth” gap could become a key challenge for many startups in 2027.
” The absence of Series C rounds this quarter highlights a challenge that has long characterized the ConTech ecosystem: the path from early traction to large-scale adoption remains difficult. Early-stage capital continues to flow, but many startups struggle to bridge the gap between raising a Series A or B and reaching the level of revenue, customer penetration, and repeatable growth required to attract later-stage investors. For founders, the message remains clear: technology alone is not enough. ” — Jose Antonio Brunet, Leader at Cemex Ventures
M&A and consolidation continued to shape the sector, with six M&A transactions recorded during Q3. The most significant was Autodesk’s $3.6B acquisition of MaintainX, a deal we already flagged as a landmark signal in our H1 report. Its size materially distorts the quarter’s headline figures, which is why we analyze it separately from core ConTech activity.
From a broader industry perspective, the transaction illustrates growing strategic interest in extending construction technology beyond design and project execution into operations, maintenance, asset management and industrial workflows. Procore’s acquisition of DroneDeploy points in a similar direction: platforms are moving to own more of the asset lifecycle and the data generated on it, from reality capture to day-to-day operations.
Q3 therefore provides further evidence of the convergence between traditional ConTech and the wider industrial technology ecosystem.
“What we are seeing is that the boundaries of ConTech are expanding. The value is no longer only in how we design and build an asset, but in how we operate and maintain it for decades. Acquirers are paying for that continuity of data, and that opens very interesting exit paths for startups working across the full lifecycle.” — Miguel Carralón, Venture Investments & Partnerships at Cemex Ventures
Artificial Intelligence has moved from an emerging investment theme to a foundational layer of ConTech. Approximately 69% of Q3 transactions involved AI-based or AI-enabled companies, broadly maintaining the roughly 70% penetration observed during H1 2026.
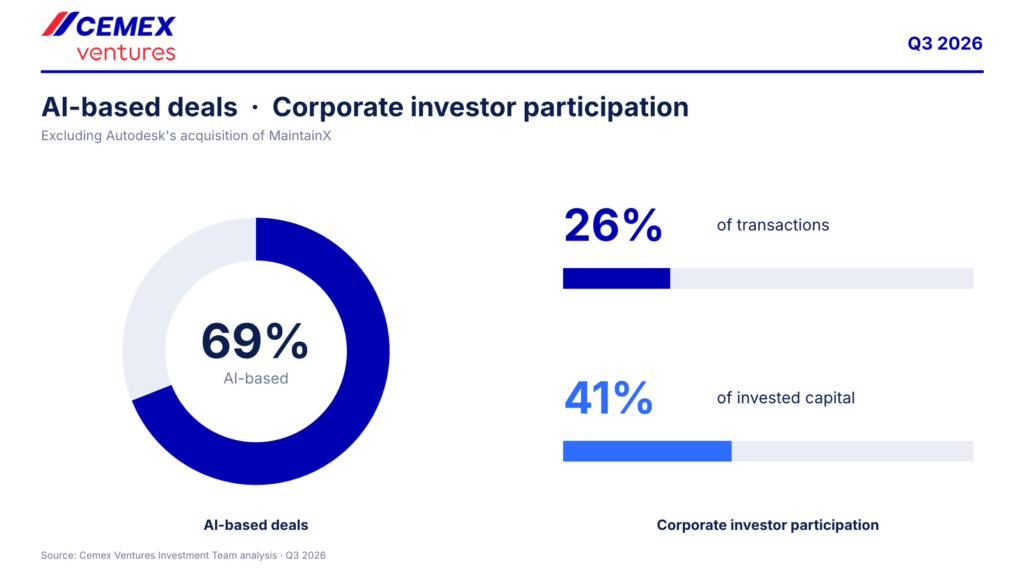
Importantly, AI activity is no longer concentrated in a single technology category. It increasingly underpins design and engineering, project management, field intelligence, robotics, autonomous equipment, reality capture and operational optimization. The consistency of this figure across 2026 suggests that AI is becoming a structural characteristic of the ConTech investment landscape rather than a temporary investment cycle.
“In our H1 report, we said the question was no longer whether a startup uses AI, but how central AI is to its defensibility. Q3 confirms it. With seven out of ten deals involving AI, the differentiator is now proprietary data, deep integration into construction workflows and measurable impact on productivity, safety or emissions.” — Jose Antonio Brunet, Leader at Cemex Ventures
Corporate investor participation moderated compared with the first half of the year but remained highly relevant. Corporates participated in 26% of Q3 transactions, versus 37% in H1, while accounting for 41% of total invested capital.
This gap between deal participation and capital deployed highlights the significant weight of strategic investors in larger funding rounds and their continued commitment to the ConTech ecosystem. Corporates are being more selective about where they enter, but when they do, they are doing it with conviction.
“Corporate venture capital brings something to construction that financial capital alone cannot: the industry itself. Access to plants, jobsites, supply chains and customers is often what turns a promising pilot into a scalable business. The fact that corporates are present in 41% of the capital deployed this quarter shows that strategic investors are not stepping back, they are concentrating their bets.” — Miguel Carralón, Venture Investments & Partnerships at Cemex Ventures
VC activity in ConTech remains stable, but the macro environment deserves close attention. Looking ahead, higher interest rates could introduce new headwinds for both VC investment and M&A activity over the coming quarters. A higher cost of capital typically reduces investors’ appetite for risk, puts pressure on startup valuations and makes fundraising more challenging, particularly for later-stage companies that require larger capital commitments.
For a market that already shows a thin middle layer between Series B and late stage, this is a factor that could accentuate the selectivity we are already observing.
“Construction has always been cyclical, and ConTech investors know it. If rates stay higher for longer, we expect valuations to adjust and fundraising timelines to stretch, especially at growth stage. But the structural drivers, from labor shortages to decarbonization and the infrastructure and data center buildout, are not going away. Disciplined companies with real traction will keep finding capital.” — Jose Antonio Brunet, Leader at Cemex Ventures
Q3 2026 marks a turning point in the ConTech investment cycle. Here are our key takeaways:
At Cemex Ventures, we will keep tracking every quarter to help founders, investors and industry partners understand where construction innovation is heading, and we will keep backing the startups that are building it.
The next wave of construction innovation is not slowing down. It is scaling up. Meet the Construction Startup Competition Finalist here
Construction Startup Competition 2026 announces the 13 finalists selected for its two remaining global stages: eight startups will pitch in Las Vegas and five in Helsinki, following the evaluation conducted by thecompetition’s global partners.
Cemex Ventures, together with BCA Singapore, Caterpillar, Dysruptek by Haskell, Ferrovial, Hilti Venture, Leonard by VINCI Group, NOVA by Saint-Gobain, Trimble and Zacua Ventures, today announced the 13 startups selected to compete at the final two global stages of Construction Startup Competition 2026.
Eight finalists will take the stage in Las Vegas during Trimble Dimensions User Conference, while five will compete in Helsinki at RecoTech during Slush Week. Together, they represent the final cohort of an edition that attracted a record 798 applications from 62 countries and brought emerging technologies from across the global built environment into one of the industry’s most established open innovation platforms.
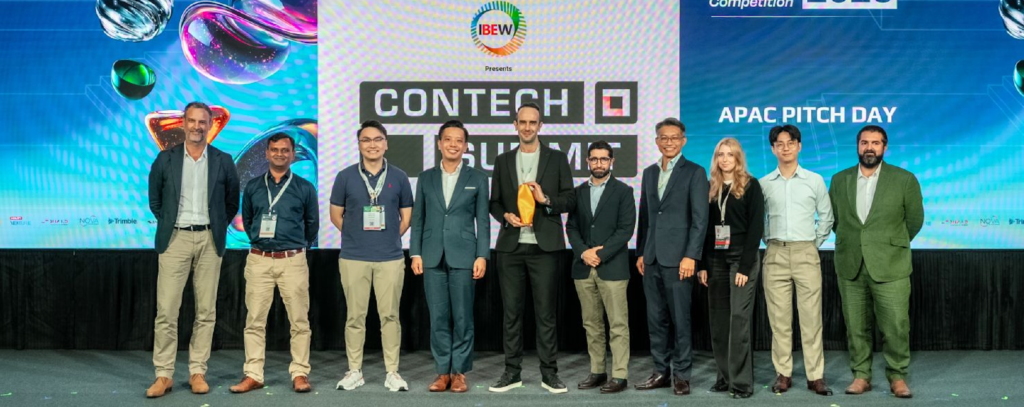
The announcement brings Construction Startup Competition 2026 into the closing chapter of its 10th edition, following the APAC Pitch Day held in Singapore, where Civils.ai became the first Gold Winner of the year.
Following the assessment of the applications by the Construction Startup Competition partners, the 13 selected startups will now present their technologies before industry experts, investors and construction leaders across two of the world’smajor innovation ecosystems.
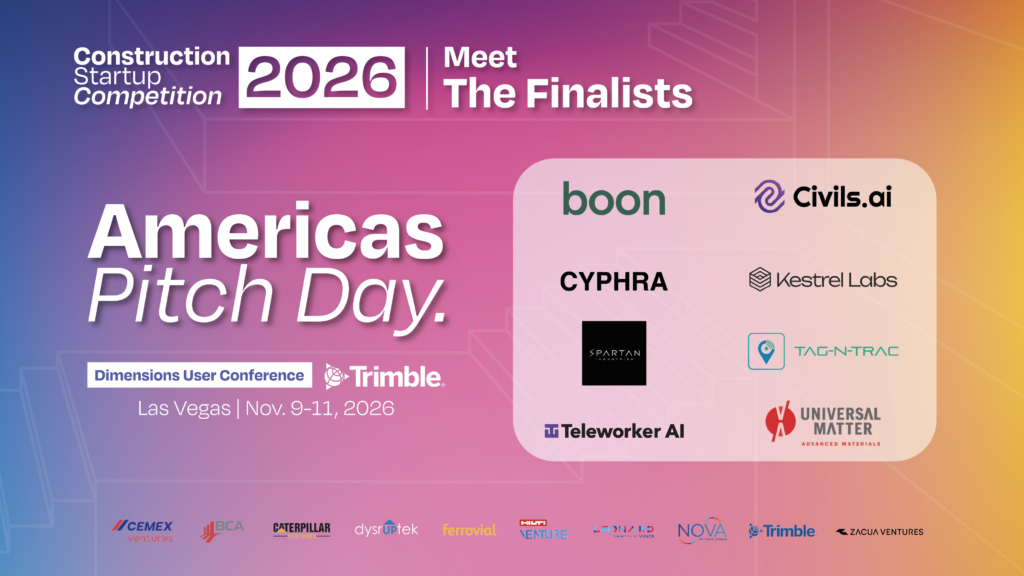
Americas Pitch Day — Meet the 8 Finalists
Universal Matter Inc. (“UMI”) (Canada): transforms carbon waste into sustainable, high-quality graphene dispersions that improve the strength of concrete while significantly reducing its GHG emissions, without increasing costs. Vertical: ClimateTech for the Built World.
Cyphra Autonomy (USA): builds PAL, an autonomous robot platform that moves materials, tools and debris across commercial construction sites, so skilled crews can stay on task. Vertical: Jobsite Productivity & Building Systems.
Teleworker AI (USA): the operating system for physical AI workforces, connecting robots, remote operators, AI agents and digital twins to automate site inspections, progress tracking, safety monitoring and facility operations. Vertical: Jobsite Productivity & Building Systems.
Civils.ai (Singapore): the AI risk platform for civil construction, estimating quantities from drawings with 90% less effort and using contract documents to manage risk, scope changes and claims. Vertical: Preconstruction Technologies.
Kestrel Labs (USA): transforms building regulations into structured, machine-readable intelligence that continuously checks BIM and CAD models, reducing project risk during design and before permitting review. Vertical: Preconstruction Technologies.
Boon AI (USA): an AI estimating platform for general contractors and subcontractors that turns 2D PDF blueprints into structured, bid-ready takeoffs in minutes, cutting estimating time by 90%. Vertical: Preconstruction Technologies.
Spartan Industries (USA): builds OpenCROS, the open operating system that coordinates heterogeneous construction robot fleets from a single control room, with a live digital twin that catches errors before they happen. Vertical: Smart Buildings & Infrastructure.
Tag-N-Trac (USA): a full-stack IoT and AI-driven platform that brings real-time, end-to-end visibility and automation to global supply chains and logistics. Vertical: Smart Manufacturing & Logistics.
European Pitch Day — Meet the 5 Finalists
Bton Holding GmbH (Germany): develops Hybrid Suspension Mixing, a two-stage processing technology for industrial concrete production that enables lower-cost, low-carbon structural concrete with lower cement demand. Vertical: ClimateTech for the Built World.
Builder Assist (France): develops Surface Assist, the first multi-task robotic arm mounted on standard aerial lifts, automating strenuous tasks such as drilling, grinding, sanding and rendering on large surfaces. Vertical: Jobsite Productivity & Building Systems.
Bimefy (Belgium): an AI-driven construction intelligence platform that links site reality to 4D BIM, connecting planning, 360° captures, drone data and live cameras to track progress and detect deviations early. Vertical: Jobsite Productivity & Building Systems.
Sensible 4 (Finland): builds retrofit autonomy and site fleet management for heavy construction fleets, combining V2X, terrain-aware perception and physics-first simulation to automate real worksite operations. Vertical: Jobsite Productivity & Building Systems.
Robotiz3d Technology Ltd (United Kingdom): captures millimetre-accurate 3D road-condition data at traffic speed and uses AI to classify every crack and pothole, turning reactive road repair into predictive maintenance. Vertical: Smart Buildings & Infrastructure.
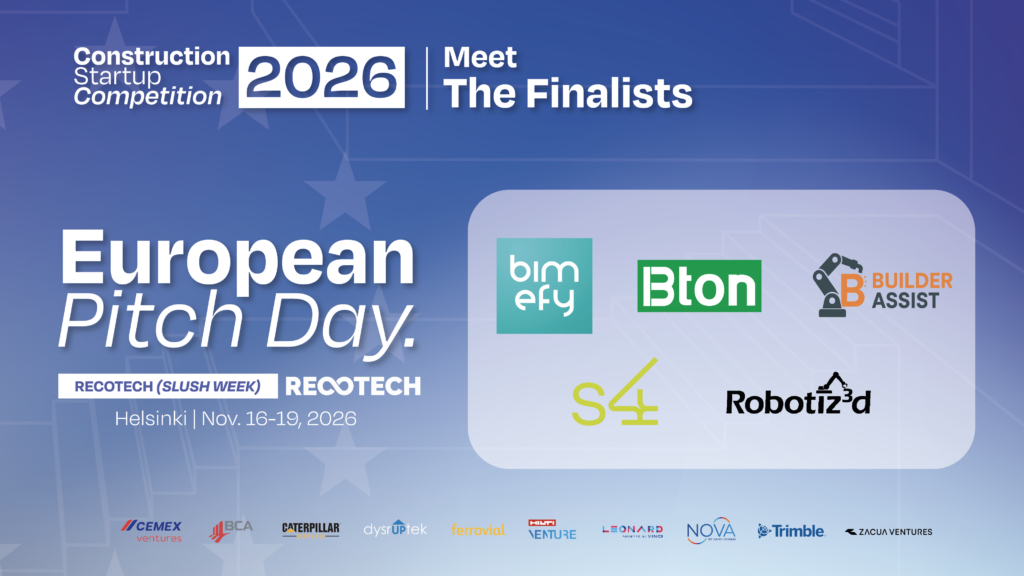
The Americas Pitch Day stage will take place as part of Trimble Dimensions User Conference & Offsite Expo 2026, held in Las Vegas from November 9–11. Helsinki will follow on November 17 at RecoTech, one of the Nordic region’s key meeting points for PropTech and ConTech and part of Helsinki’s wider Slush Week innovation ecosystem.
Beyond setting a new participation record, the 2026 application pool provides a snapshot of where entrepreneurs see some of the construction industry’s most immediate opportunities for transformation.
The competition received 798 applications from 62 countries, 40.3% more than in 2025. Europe and North America accounted for 64% of applications, while APAC represented 23%, Latin America 7%, the Middle East 5% and Africa 1%.
The technologies submitted also reveal where founders are concentrating their efforts. Jobsite Productivity & Building Systems was the largest category, accounting for 32.5% of applications, followed by ClimateTech for the Built World at 22.8% and Preconstruction Technologies at 21.7%. Smart Buildings & Infrastructure represented 13%, while Smart Manufacturing & Logistics accounted for 9.9%.
Taken together, the figures point to an ecosystem increasingly focused on technologies capable of improving productivity, digitizing workflows, reducing environmental impact and connecting physical construction processes with data, automation and intelligent systems.
From this global pool, the Construction Startup Competition partners have now narrowed the field to the startups that will represent the final two stages of the 2026 edition.
The first name in the Construction Startup Competition 2026 Hall of Fame has already been decided.
Civils.ai was named APAC Gold Winner following the first Pitch Day of the 2026 edition, held in Singapore during International Built Environment Week (IBEW).
The startup competed alongside Arbel.ai, Bton.io, ConcreteAI and LIGHTYX, securing the Gold distinction with its AI-powered platform designed to automate repetitive and error-prone preconstruction tasks. Its technology combines AI-drivenquantity takeoffs with the intelligent review and cross-checking of construction drawings, specifications and project documentation.
Singapore marked the beginning of the Competition’s global final phase and established Civils.ai as the first Gold Winner of the 2026 edition.
Now, attention turns west.
The final stages of Construction Startup Competition 2026 will bring the competition into two very different but complementary innovation environments.
In Las Vegas, eight startups will present their solutions during Trimble Dimensions, connecting the finalists with construction and technology professionals from across the global Trimble ecosystem. The stage will determine the Competition’sGold, Silver and Bronze medals.
For the fourth consecutive year, the Construction Startup Competition returns to The Venetian in Las Vegas, reinforcing a stage that has become a key meeting point for some of the most promising emerging companies in ConTech.
Last year’s Gold Winner, Gravis Robotics, offers a compelling example of what can follow. The Swiss startup took the top prize at the 2025 Las Vegas Pitch Day with its robotic intelligence technology for automating heavy constructionmachinery. Less than a year later, in August 2026, Gravis Robotics announced a $200 million Series A investment from SoftBank to accelerate the global deployment of its autonomous heavy-equipment technology.
Its trajectory from the Las Vegas stage to one of the construction robotics sector’s most significant recent funding rounds illustrates the ambition behind Construction Startup Competition: identifying emerging technologies and connecting theirfounders with an international ecosystem capable of supporting their next stage of growth.
One week later, Helsinki will bring five finalists to RecoTech on November 17. Held during Slush Week, the event connects startups with investors, corporations and decision-makers from the Nordic and international built environmentecosystem and will crown the European Gold Winner of Construction Startup Competition 2026.
Together with the Singapore stage, Las Vegas and Helsinki complete a global journey designed not only to identify promising technologies, but to connect founders with the corporations, investors and strategic partners capable of helping thosetechnologies move from innovation to adoption and international scale.
After 798 applications, 62 countries and three global stages, Construction Startup Competition 2026 is approaching the moment when its next generation of construction innovators will be fully revealed.
Singapore has already crowned its Gold Winner. Las Vegas and Helsinki are next.
Cement has a problem that better energy efficiency alone can’t fix. Between 60% and 65% of its emissions don’t come from burning fuel; they come from the chemical reaction itself, calcining limestone to produce clinker. That’s a process emission, not an energy emission, and it means something uncomfortable: no matter how clean the heat source gets, that portionof the CO₂ keeps coming out. According to the World Economic Forum, this is exactly why carbon capture, utilization, and storage (CCUS) is a lever the cement sector can’t avoid on its path to net zero.
This matters well beyond the plant gates. Buildings, infrastructure, and everything built with cement inherit whatever emissions were embedded in the material before it ever left the factory. A developer can specify the most efficient building in the world, but if the concrete underneath it was made without addressing process emissions, a meaningful chunk of that project’s carbon footprint was already locked in before construction even started. That’s precisely why CCUS sits at the center of how the sector thinks about genuinely low-carbon construction, not just efficient buildings.
But “CCUS” isn’t just one technology. It’s an umbrella term covering a carbon-management chain with a common first step and two possible pathways for the captured CO₂. First, CO₂ is captured at the emission source. From there, it can either be utilized (i.e. converted into new compounds, mineralized in other cementitious materials) or transported for permanent geological storage. Understanding how these stages fit together isn’t an academic exercise; instead, a set of techno-economic factors determines which solution/s and infrastructure make sense for each plant, each geography, and each investment horizon.
And it’s worth clearing up a common confusion right away: CCUS isn’t an alternative to cutting clinker content, increasing alternative fuel rates or electrifying kilns. It’s the lever that kicks in once the others have already been pushed as far as chemistry allows. No cement producer is reaching net zero purely by optimizing its mix or switching fuels, at some point in the equation, a fraction of process emissions has to be captured and then reused or stored. So the real question isn’t whether the sector will need CCUS, but how capture can be combined with utilization or storage in each context.
This is the most intuitive part of the process: pulling CO₂ out of a cement plant’s flue gas before it’s released. The challenge isn’t really capturing it per se, since other industries have known how to do that for decades; it’s doing it at a cost that doesn’t wreck the economics of a plant already running on thin margins.
This is where the sector has moved from promise to real execution in recent years, and two companies from the Cemex Ventures portfolio illustrate two parallel ways of tackling the problem.
Carbon Clean, a UK-based carbon capture company, bets on solving the size problem with its CycloneCC technology: its solution is fully modular, with a footprint up to 10 times smaller than conventional capture systems, and is on track to bring capture costs below $30 per ton of CO₂. Cemex was one of its earliest strategic partners, investing in the company in 2021 and subsequently collaborating on a front-end engineering design (FEED) study for an industrial-scale carbon capture unit at Cemex’s Rüdersdorf plant in 2022. The partnership is now focused on planning the deployment across Cemex’s footprint, as technology is further optimized through prospective pilot campaigns.
KC8 Capture Technologies, an Australian company backed by Cemex Ventures alongside Woodside Energy and SABIC, attacks the same problem from a different angle: a proprietary, non-toxic and non-volatile solvent that captures up to 95% of CO₂ from heavy industrial sources, (e.g. cement, steel, power generation), at a capital cost up to 50% lower than amine-based solutions, and with roughly 15% better energy efficiency. The startup is currently piloting at industrial scale at the National Carbon Capture Center in Alabama (USA), and short-term results will trigger future collaborations with Cemex to further derisk technology and potential business cases.
What matters in both cases isn’t just the technology itself, but the pattern behind it: neither started as a lab promise a manufacturer adopted on faith. Both have advanced through close collaboration with a cement producer, with Cemex actively supporting their development and industrial scale-up. That, ultimately, is what can make the difference between a capture technology that remains a technical concept and one that has a credible path to commercial deployment.”
And cost remains the variable that decides everything. For years, the reference price the industry has chased is getting below $30–40 per ton of CO₂ captured, the threshold at which the technology stops being a subsidized sustainability project and starts making economic sense on its own. Both Carbon Clean and KC8 have built their value proposition explicitly around that number, which explains why both have pulled off something rare in climate tech: getting a cement producer to offer up its own plant as a testing ground, rather than waiting for the technology to mature somewhere else first.
The first pathway after capture uses CO₂ as an input to produce lower-carbon derivatives (like construction materials). Through mineralization, CO₂ reacts with calcium- or magnesium-rich materials and is converted into stable mineral forms, effectively locking the carbon into the material itself. Carbon Upcycling is a sound example of this approach. Its technology uses CO₂ to transform industrial waste streams and other mineral materials into higher-performing cement additives, helping reduce the clinker content—and therefore the embodied carbon—of cement. Rather than treating CO₂ solely as a waste stream that needs to be transported and stored, the process turns it into an input for producing construction materials.
Cemex first invested in Carbon Upcycling in 2022, and that same year the two companies began working together to establish the world’s first commercial-scale plant producing cement additives by sequestering CO₂ at Cemex’s Rugby cement plant. The partnership is now focused on exploring new opportunities and feedstocks to scale the technology across multiple Cemex’s operations.
Utilization has one clear advantage over geological storage: it doesn’t require transport or geological storage infrastructure. The CO₂ becomes part of the product itself, potentially avoiding the need for the transport and geological storage infrastructure required by conventional carbon capture and storage. This can simplify the deployment pathway, particularly where the captured CO₂ can be integrated directly into the production of new construction materials.
The challenge, however, is that the scale of CO₂ utilization is ultimately linked to the availability and economics of suitable feedstocks and end markets for the resulting materials. The opportunity is therefore not only to permanently mineralize CO₂, but to do so while producing a commercially valuable product that can displace higher-carbon materials. This creates a fundamentally different deployment model from traditional carbon capture and storage: rather than building an entirely new value chain comprising capture, transport and storage infrastructure, the technology can be integrated into existing materials production and create value from both the CO₂ and the waste material.
The second pathway after capture is the most ambitious from an infrastructure standpoint, and the most recent to reach real industrial-scale operation within the cement sector. It means capturing CO₂, liquefying it, transporting it (usually by ship or pipeline), and storing it permanently in deep geological formations – typically beneath the seabed.
The most significant example in the sector to date is Brevik CCS project in Norway, which opened in 2025 as the first industrial-scale capture facility in the history of the global cement industry. The plant captures around 400,000 tons of CO₂ a year, 50% of the facility’s emissions, which is liquefied and shipped to Northern Lights, where it is temporarily stored before being transported through a. 110-kilometer pipeline and injected approximately 2,600 meters beneath the seabed for permanent storage.
What makes this case particularly significant isn’t just the scale, but the full value chain it represents: plant-level capture, maritime transport, intermediate storage, and finally permanent geological injection, all operating as an integrated system across several specialized companies. It provides an important real-world reference for an industry that had previously relied largely on pilot projects, feasibility studies, and individual components of the value chain.
Of the two post-capture pathways, geological storage is by far the one requiring the most coordination between companies that don’t necessarily compete with each other but have to sync perfectly: the (cement) producer that captures, the shipping company that transports, and the site operator that stores. That complexity is also why, until Brevik, this pathway existed mostly in technical papers and feasibility studies. Northern Lights, for instance, already counts industrial customers from sectors well outside cement, from a waste-to-energy plant in Oslo to a chemical plant in the Netherlands, pointing toward a future model: shared storage infrastructure across industries, rather than each sector building its own from scratch.
Capture is the common first step. After that, utilization and geological storage are two downstream routes whose suitability depends on the plant, scale, geography and available/required infrastructure.
The GCCA estimates that carbon capture, utilization, and storage accounts for 36% of the reduction levers in its 2050 roadmap to net-zero cement, a good indicator of how much weight this family of technologies carries in the overall equation, well ahead of what any single lever, like clinker reduction or the energy transition, can deliver on its own.
For a cement producer, the choice after capture —utilization or geological storage— is a strategic decision, shaped by plant location, nearby transport infrastructure, available capital and the market for the resulting green(er) cement or concrete.
For investors backing these startups, and this is where a corporate venture capital fund like Cemex Ventures comes in, the read is different: it’s not about betting on a single winning technology, but building a portfolio of complementary solutions that cover the different scenarios a global cement business actually operates in. Carbon Clean and KC8 aren’t really competing so much as each competing against the status quo of capturing nothing at all. And neither competes directly with carbon utilization solutions like Carbon Upcycling, which solve a different problem at a different point in the value chain.
That, ultimately, is the lesson: CCUS is not a choice between mutually exclusive pathways. Capture is the common starting point; utilization and geological storage are the two downstream routes needed to tackle process emissions other decarbonization levers cannot eliminate.
Cemex Ventures and its global partners announce the first Gold Winner of the 2026 edition following the APAC Pitch Day held in Singapore. The competition will continue with its next Pitch Days in Las Vegas and Helsinki.
Cemex Ventures, together with its partners Caterpillar, Dysruptek by Haskell, Hilti Ventures, Leonard by VINCI, NOVA by Saint-Gobain, Trimble, Zacua Ventures and the Building and Construction Authority (BCA) of Singapore, has announced Civils.ai as the APAC Gold Winner of Construction Startup Competition 2026.
The startup secured the first Gold Winner title of this year’s competition after pitching its solution alongside four other finalists during the APAC Pitch Day in Singapore.
The event represents the first of three Pitch Days that will define the Gold Winners of Construction Startup Competition 2026, with the next stages set to take place in Las Vegas and Helsinki, during RecoTech.
Five startups were selected to compete in Singapore:
Following the jury evaluation, Civils.ai was selected as the APAC Gold Winner for its AI-powered platform designed to automate some of the most repetitive and error-prone tasks in preconstruction. By combining AI-driven quantity takeoffs with intelligent review and cross-checking of complex construction drawings, specifications and project documentation, Civils.ai enables teams to significantly reduce manual effort, improve accuracy and identify potential issues earlier in the project lifecycle. Its construction-specific approach has the potential to increase the capacity of estimating and preconstruction teams while enabling faster, more reliable and data-driven decision-making across the industry.
The APAC Gold Winner award was presented to Civils.ai by Jesús Ortiz, Head of Cemex Ventures, and Mr Alvin Tan, Minister of State in the Ministry of Foreign Affairs and the Ministry of National Development of Singapore, recognizing the startup’s achievement as the first Gold Winner of Construction Startup Competition 2026.
The APAC Pitch Day was held in Singapore in the context of International Built Environment Week (IBEW), bringing together startups, construction companies, investors, technology providers and industry leadersfrom across the built environment ecosystem.
The Singapore event marks the beginning of the final stage of Construction Startup Competition 2026 and the first opportunity this year to recognize one of the startups selected through the competition’s global scouting process.
With its selection as APAC Gold Winner, Civils.ai becomes the first of three Gold Winners to be announced during the 2026 edition.
The competition will now move to its next two Pitch Days in Las Vegas and Helsinki, where additional finalists will pitch their solutions before industry experts and compete for the remaining Gold Winner titles.
Through this global format, Cemex Ventures and the competition partners aim to connect emerging technologies with some of the leading players across the construction value chain, creating opportunities forstartups to engage with corporates, investors and potential strategic partners.
Construction Startup Competition is an initiative led by Cemex Ventures together with a global network of industry partners, combining their reach, sector expertise and innovation ecosystems to identify startups with the potential to transform construction.
The 2026 edition brings together Cemex Ventures, Caterpillar, Dysruptek by Haskell, Hilti Ventures, Leonard by VINCI, NOVA by Saint-Gobain, Trimble and Zacua Ventures, with BCA Singapore supporting the APAC stage of the competition.
Together, the partners evaluate technologies and business models across five strategic areas:
Preconstruction; Jobsite Productivity & Building Systems; ClimateTech for the Built World; Smart Manufacturing & Logistics; and Smart Buildings & Infrastructure.
This year’s edition received a record 798 applications from 62 countries, representing a 40.3% increase compared with 2025 and reinforcing the competition’s position as a global meeting point betweenconstruction innovation, startups and industry.
The initiative seeks not only to identify promising technologies, but also to facilitate connections between startups and leading construction companies, exploring opportunities ranging from pilots and commercialpartnerships to investment and broader strategic collaboration.
With the APAC Pitch Day now completed, Construction Startup Competition 2026 moves to the next stage of its global journey.
Singapore has revealed the first Gold Winner. Las Vegas and Helsinki will decide the next two.
The Construction Startup Competition 2026 has reached its first major milestone.
Following a record-breaking edition with 798 applications from 62 countries, six innovative startups have been selected to compete at the APAC Pitch Day, taking place on September 2, 2026, during the International Built Environment Week (IBEW) in Singapore.
As the competition celebrates its 10th edition, the APAC Pitch Day marks the beginning of a global journey that will bring together the world’s most promising ConTech startups with leading investors, construction companies, and industry decision-makers.
The 2026 edition has already become the most competitive in the history of the Construction Startup Competition.
This year’s figures reflect the accelerating pace of innovation across the built environment:
The growing participation confirms a clear industry trend: construction is embracing technology faster than ever before, with startups playing a central role in solving some of the sector’s biggest challenges.
After a rigorous evaluation process conducted by industry experts and venture capital partners, the following startups have been selected to present their solutions in Singapore.
Leveraging artificial intelligence to improve engineering workflows and accelerate decision-making, Arbel.ai is helping construction professionals work faster and more efficiently through intelligent automation.
Civils.ai applies AI to civil engineering, enabling infrastructure teams to process complex engineering documentation and technical information more efficiently while reducing manual effort.
ConcreteAI is transforming concrete monitoring through advanced AI-powered analytics, helping construction teams optimize quality, performance, and project execution.
Bton.io is digitizing construction workflows through connected technologies that improve collaboration, operational efficiency, and project visibility across the construction lifecycle.
Dig Robotics is bringing robotics into construction operations, helping automate repetitive and labor-intensive processes while increasing productivity and precision on-site.
LIGHTYX combines laser-guided technologies with digital construction solutions to improve accuracy, streamline execution, and reduce inefficiencies during project delivery.
The APAC Pitch Day will be held as part of the International Built Environment Week (IBEW), one of Asia-Pacific’s leading events for innovation in the built environment.
Bringing together government agencies, developers, contractors, investors, technology providers, and startups, IBEW provides the perfect stage for emerging companies to showcase breakthrough solutions addressing the industry’s most pressing challenges.
For the selected startups, this represents far more than a pitching competition, it is an opportunity to gain international visibility, connect with strategic partners, and accelerate commercial growth across the region.
The Construction Startup Competition has become one of the construction industry’s leading global startup initiatives thanks to the collaboration between major corporate innovators and venture capital partners committed to accelerating construction technology adoption.
The 2026 APAC Pitch Day is supported by:
Together, these organizations continue building bridges between startups and the companies transforming the future of construction.
Singapore is only the beginning.
The APAC Pitch Day represents the first stop in the global Construction Startup Competition 2026 journey, where outstanding startups will have the opportunity to demonstrate how technologies such as artificial intelligence, robotics, digital engineering, and advanced construction systems are reshaping the built environment.
With unprecedented participation and an exceptional level of innovation, the 10th edition reinforces one clear message:
The future of construction is already being built—and its next chapter starts in Singapore.
By the Cemex Ventures Investment Team | July 2026
The construction technology (ConTech) investment landscape delivered a strong signal in the second quarter of 2026: capital is back in motion. After a cautious start to the year, Q2 2026 closed with $1.031 billion in disclosed investment volume across 84 transactions, a 30% increase in deployed capital compared to Q2 2025. This resurgence, concentrated in productivity-enhancing technologies and AI-native startups, reflects a market that is becoming more selective, more strategic, and increasingly convinced that artificial intelligence is not a trend but a foundational transformation for the built environment.
At Cemex Ventures, we track global ConTech investment flows every quarter to map where innovation capital is going, and what it tells us about the future of construction. This report covers Q2 2026 data and full H1 2026 context, surfacing the key themes, geographies, and deal dynamics shaping the industry right now.
The headline numbers from Q2 2026 tell an interesting story. Investment volume jumped 30% year-over-year to just over $1 billion, yet the number of transactions fell 8%, from 92 deals in Q2 2025 to 84 in Q2 2026. This divergence between capital deployed and deal count points to a broader industry dynamic: investors are concentrating more capital into fewer, more mature bets. Check sizes are growing, diligence bars are rising, and the speculative flurry of earlier years has given way to conviction-driven deployment.
This is not a sign of weakness. It is a sign of maturity.
” ConTech deal activity remains within historical parameters and should not be interpreted as a sign of weakness. While transaction volume has declined compared to last year, we do not observe any meaningful market contraction. Instead, this moderation may be an indication of a maturing ecosystem, where investors are becoming more selective and concentrating capital in higher-quality opportunities. Overall, current activity levels remain healthy and do not raise concerns about the underlying strength of the sector. “ — Miguel Carralón, Investments & Partnerships Manager, Cemex Ventures
The ConTech ecosystem is shedding the excess of the 2021–2022 boom cycle and rebuilding around companies that can demonstrate real revenue, measurable ROI, and genuine product-market fit. The investors still writing checks, and they are writing larger ones, believe in the long-term thesis: construction is one of the world’s largest and least digitized industries, and the window to back the companies that will transform it remains wide open.
Zooming out to the full first half of 2026, total disclosed investment volume reached $2.884 billion across 153 transactions. On the surface, this represents a 19% decline in invested capital and a 20% drop in deal count versus H1 2025. But surface-level numbers require context.
Critically, the $2.884B figure excludes at least three major undisclosed acquisitions completed during the first half of the year. Incorporating reasonable estimates for these transactions, total H1 2026 investment volume is likely closer to $4.5 billion. The reduction in deal activity is real, but 153 transactions across six monthsreflects a healthy, active market.
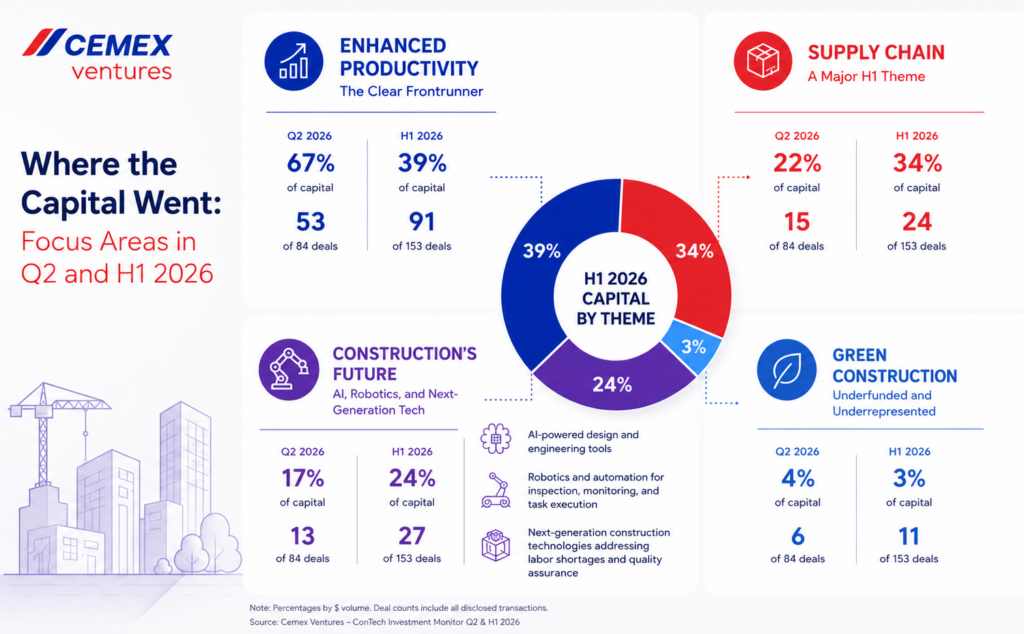
The dominant investment theme of Q2 2026, and the entire first half, was Enhanced Productivity. This category captured 67% of Q2 investment volume by dollar amount and 39% of H1 2026 capital. By deal count, Enhanced Productivity accounted for 53 of 84 transactions in Q2 and 91 of 153 in H1.
Investors are backing platforms that improve efficiency, automate repetitive workflows, digitize project execution, and reduce rework on construction sites. The appetite here is enormous, and it is easy to understand why: construction productivity has stagnated for decades relative to other industries. The companies solvingthis problem, whether through project management software, AI-powered scheduling, or digital twins, are addressing a genuine and urgent pain point for owners, contractors, and developers worldwide.
Supply Chain technologies emerged as the second-largest investment category in H1 2026, capturing 34% of invested capital and 24 transactions over the six month period. This reflects a sustained wave of investment in logistics optimization, procurement digitization, materials tracking, and supplier network management.
The construction supply chain remains one of the most fragmented and opaque in any major industry. Material delays, cost overruns, and lack of real-time visibility have long plagued projects at every scale. The startups attracting capital here are applying AI and data infrastructure to make the supply chain predictable, transparent, and responsive, capabilities the industry desperately needs.
“Supply chain is where projects are won or lost long before anyone sets foot on a jobsite. The surge of investment in this space reflects a growing understanding that digitizing procurement and logistics isn’t optional , it’s a competitive necessity for any serious contractor or developer.” — Jose Antonio Brunet, Principal, Cemex Ventures
The Construction’s Future category, encompassing AI-native design tools, robotics, autonomous systems, and advanced manufacturing, represented 17% of Q2 investment volume and 24% of H1 capital. With 13 deals in Q2 and 27 across H1, this category is punching above its weight in terms of strategic significance.
Three investment sub-themes stand out: AI-powered design and engineering tools that accelerate blueprint generation, optimize space utilization, and help ensure regulatory compliance; robotics and automation for inspection, monitoring, and task execution on jobsites; and next-generation construction technologiesaddressing labor shortages and quality assurance. These are the technologies that will define construction over the next decade.
Green Construction captured just 4% of Q2 investment volume (6 transactions) and 3% of H1 capital (11 deals). For an industry under significant pressure to decarbonize, and a regulatory environment in Europe and beyond that is tightening fast, this allocation remains strikingly low.
The opportunity is clear. The capital is not following it yet. This gap between sustainability imperative and investment reality is one of the defining tensions in ConTech right now, and one we expect to close as carbon reporting requirements, ESG mandates, and green procurement standards become unavoidable.
“Green Construction is still waiting for its inflection point. The regulatory pressure is mounting particularly in Europe; and the corporate sustainability commitments are real. The question is not whether capital will flow into this space, but when.” — Miguel Carralón, Investments & Partnerships Manager, Cemex Ventures
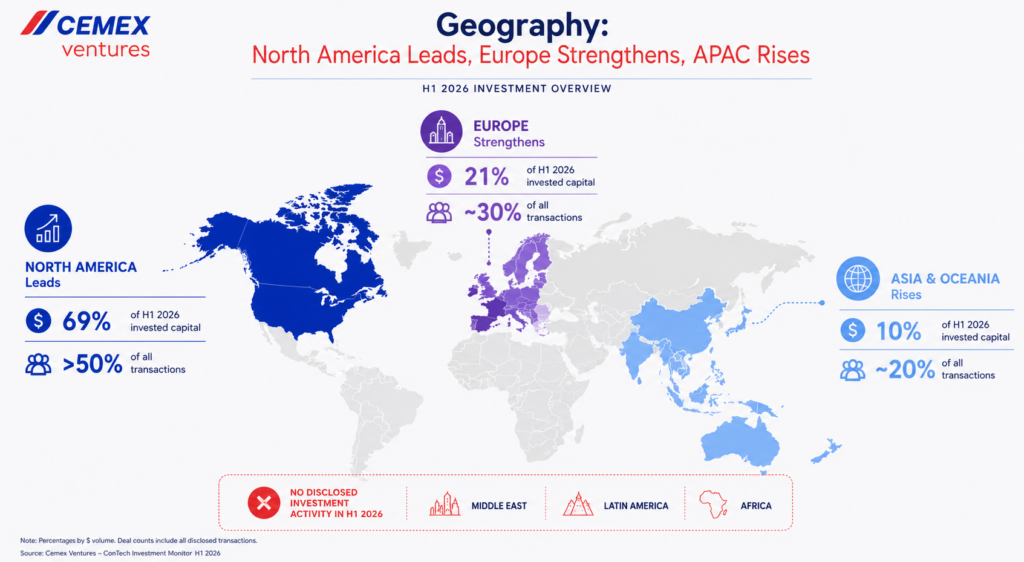
From a geographic perspective, the investment landscape remains heavily concentrated in three regions.
North America dominated H1 2026 with 69% of total invested capital and slightly more than half of all transactions. The U.S. market continues to lead in deal activity, check size, and the density of mature ConTech companies approaching growth and late-stage rounds. The concentration of strategic corporate investors and institutional venture capital in North America gives the ecosystem structural advantages that are difficult to replicate elsewhere in the short term.
Europe ranked second, attracting 21% of H1 invested capital and close to 30% of all deals. The gap between Europe’s share of capital (21%) and its share of deal count (approximately 30%) reflects smaller average deal sizes, but also a vibrant, diverse startup ecosystem spanning the UK, Germany, the Nordics, France, and the Iberian Peninsula. European ConTech continues to attract both local and cross-border investors, and the region’s strong regulatory push around sustainability and digitization is creating tailwinds for startups in green construction, compliance tech, and supply chain management.
Asia and Oceania accounted for 10% of H1 investment volume but nearly 20% of transactions, a pattern consistent with smaller deal sizes and a very active early-stage startup environment. Markets including Australia, Japan, Singapore, and India are generating significant entrepreneurial activity in construction digitization, and investor engagement in the region is deepening.
Notably, the Middle East, Latin America, and Africa recorded no disclosed investment activity in H1 2026. This does not necessarily mean deal activity is absent, it reflects limited public disclosure, but it does underscore the continued concentration of the tracked ConTech investment universe in three core geographies.
The breakdown of H1 2026 transactions by round type confirms that early-stage investing continues to dominate ConTech. Approximately 70% of all deals fell between Pre-Seed and Series A (108 transactions), while the remaining 30% corresponded to growth and later-stage rounds: 15 Series B, 2 Series C, 8 late-stagetransactions, 9 M&A deals, and 11 classified as other.
This distribution has two important implications. First, investors remain excited about the long-term opportunity in construction technology and are actively seeding the next generation of solutions, even as the overall funding environment has become more selective. Second, the pipeline of companies moving from early togrowth stage will determine whether H1 2026’s early-stage enthusiasm translates into a robust mid-stage ecosystem in 2027 and 2028.
The M&A activity is equally notable. Nine disclosed acquisitions in H1 2026 signal that the consolidation phase in ConTech is well underway, as larger platform players absorb specialized capabilities to strengthen their product suites.
Three strategic acquisitions during H1 2026 deserve particular attention because they reveal the strategic priorities of the industry’s largest platform providers.
Procore acquired DataGrid. Autodesk acquired Rhumbix. Trimble acquired Document Crunch. In all three cases, the acquirer targeted an AI-native company to strengthen a critical segment of its platform and embed artificial intelligence more deeply into construction workflows. These are not defensive acquisitions, they are offensive moves by companies that recognize AI integration as a competitive necessity.
And then there is the headline transaction of the period: Autodesk’s announced intention to acquire MaintainX for approximately $3.6 billion. This deal is a statement of strategic intent. Autodesk is no longer content to own design and preconstruction workflows; it wants to extend its platform into operations, facilitiesmanagement, asset lifecycle, and Industrial AI. For a company that has historically lived in the design phase, MaintainX gives Autodesk a credible foothold in the operational world that follows. If completed, this acquisition could fundamentally redefine Autodesk’s addressable market and intensify platform competitionacross the full construction lifecycle.
Perhaps the most striking data point from H1 2026 is this: approximately 70% of all ConTech transactions involved AI-enabled startups. This figure is not incidental, it is structural.
AI has stopped being a differentiator and started being a baseline expectation. Across Enhanced Productivity, Supply Chain, Construction’s Future, and even Green Construction, AI capabilities are being embedded into the core product architectures of the most fundable companies. Investors are no longer asking “does thisuse AI?” They are asking “how deeply is AI integrated, and how defensible is the resulting moat?”
Importantly, AI is not a separate vertical in ConTech, it is an enabling layer that cuts across every category. This distinction matters for how investors think about portfolio construction and how founders position their companies.
“We no longer evaluate startups by asking whether they use AI. We evaluate them by asking how central AI is to their defensibility. A company that has bolted on a chatbot is very different from one that has built its entire data and product architecture around AI capabilities from day one.” — Jose Antonio Brunet, Principal, Cemex Ventures
One of the most consequential trends in H1 2026 was the record level of participation from strategic corporate investors, who joined 37% of all transactions during the period. This is the highest level of corporate venture and strategic co-investment activity the ConTech market has seen.
Strategic investors, including construction companies, materials manufacturers, real estate developers, and engineering firms, bring more than capital to the table. They provide distribution, pilots, domain expertise, and market credibility that financial investors cannot replicate. Their growing presence signals that theconstruction industry itself is becoming a more active participant in shaping its own technological future, not merely a passive customer of innovation.
Where are strategics placing their bets?
The three investment themes gathering the interest from stratic investors are: project management and workflow optimization platforms that improve collaboration and data flow across the construction value chain; robotics and automation systems for inspection, monitoring, and task execution on active jobsites; and AI-powered design and engineering toolsthat accelerate blueprinting, support regulatory compliance, and optimize material consumption.
For startups, landing a strategic investor at an early stage has become a meaningful validation signal. For the ecosystem, it accelerates the path from pilot to deployment and helps close the gap between promising technology and real-world adoption.
Reading the Q2 and H1 2026 data together, several conclusions emerge:
The ConTech market is consolidating around quality. Fewer deals with larger check sizes reflect a flight to conviction. Companies that can demonstrate traction, unit economics, and scalability are attracting capital; those that cannot are finding the environment significantly harder.
AI is now the price of admission. Seventy percent AI penetration across transactions is not a coincidence. The companies raising capital are, in most cases, AI-native or AI-integrated by design. This will only accelerate.
Productivity, supply chain and new construction methods will remain the core investment thesis. Together, these categories accounted for amost all H1 capital. They address the industry’s most immediate and measurable pain points, and the total addressable market for both remains enormous.
Green Construction needs a catalyst. With 3% of H1 capital, sustainability-focused ConTech is significantly underfunded relative to the urgency of the decarbonization challenge. Regulatory pressure, net-zero commitments from major owners and developers, and maturing carbon accounting standards may provide thatcatalyst in H2 2026 and beyond.
The M&A wave is real and accelerating. The Autodesk-MaintainX deal alone represents a potential $3.6B transaction. Combined with the Procore, Trimble, and other strategic acquisitions, the platform consolidation narrative is becoming one of the defining stories in construction technology.
At Cemex Ventures, we remain committed to tracking, analyzing, and participating in the ConTech investment ecosystem. Q2 2026 confirmed what we have long believed: the construction industry is at an inflection point, and the companies building the technologies that will define its future are raising capital, findingcustomers, and scaling faster than ever.
The next wave of construction innovation is not coming. It is already here.
Construction Startup Competition has officially closed applications for its landmark 10th edition, reaching an unprecedented milestone with 798 startup applications from around the world, the highest number received since the competition was established in 2017. Compared to the previous edition, the competition achieved a 40.3% increase in applications, further strengthening its position as one of the world’s leading open innovation platforms dedicated to the construction industry.
The record-breaking edition reflects the accelerating pace of innovation across construction and sends a strong message to the market: the global ConTech and Cleantech ecosystem has never been more active. Increasing numbers of entrepreneurs are developing technologies that address the industry’s biggest challenges, while major corporations continue embracing open innovation as a strategic driver of transformation.
For the past decade, Construction Startup Competition has connected promising startups with leading construction companies, investors, and decision-makers worldwide. Beyond visibility, the initiative has become a launchpad for emerging companies looking to validate technologies, secure pilot opportunities, establish commercial partnerships, and scale internationally.
After a series of promotional events and a well-coordinated marketing and communications campaign, the Competition successfully attracted applications from 62 countries. A total of 64% of applicant startups are based in Europe and North America, while the remaining applications came from APAC (23%), Latin America (7%), the Middle East (5%), and Africa (1%).
“One of the most notable outcomes of this year’s edition was the 181% increase in applications from startups based in Asia and Oceania. This strong growth supports the Competition’s strategy of positioning itself as a gateway for APAC startups seeking to connect with leading global corporates, investors, and industry stakeholders, while expanding their reach into international markets,” said Miguel Carralón, Investment & Partnerships Manager.
This year’s edition focused on five new strategic innovation areas aligned with the priorities of the sponsoring partners, while also reflecting the challenges and opportunities that resonate most strongly with startups. Preconstruction Tech accounted for 21.7% of all applications, followed by Jobsite Productivity & Building Systems, which attracted 32.5% of submissions. ClimateTech for the Built World represented 22.8% of applications, while Smart Manufacturing & Logistics accounted for 9.9%. Finally, Smart Buildings & Infrastructure made up 13% of all applications received.
The distribution of applications across these focus areas highlights the growing industry demand for solutions that enhance productivity, accelerate digital transformation, improve sustainability, and drive greater efficiency throughout the built environment value chain.
Following the application phase, participating partners will now evaluate submissions before selecting the startups advancing to this year’s international Pitch Days in Singapore (IBEW), Las Vegas (Trimble Dimensions), and Helsinki (Recotech & Slush).
“Receiving 798 applications, and surpassing last year’s participation by more than 40%, is a remarkable achievement for the Construction Startup Competition and for the entire construction innovation ecosystem. Ten years ago, we launched this initiative with the ambition of connecting visionary entrepreneurs with the companies shaping the future of construction,” said Jesús Ortiz, Head of Cemex Ventures.
“Today, the record participation confirms that this vision is stronger than ever. It demonstrates not only the increasing relevance of the Competition, but also the growing maturity of the global ConTech ecosystem and the industry’s willingness to embrace innovation through collaboration. We are incredibly proud of what this platform has become over the past decade and excited to discover the technologies and founders that will define the next generation of construction.”
About Construction Startup Competition
Since its first edition in 2017, startups from more than 80 countries have participated in the biggest challenge aimed at startups in the construction industry, the Construction Startup Competition. Many startups have gone on to collaborate with the participating companies after applying to the Competition. Over ten editions, the initiative has established itself as one of the industry’s leading global open innovation platforms, connecting entrepreneurs with corporations, investors, and strategic partners to accelerate the adoption of breakthrough technologies across the built environment.
About Cemex Ventures
Launched in 2017, Cemex Ventures focuses on helping overcome the main challenges and capitalizing on the opportunity areas in the construction ecosystem through sustainable solutions. Cemex Ventures has developed an open collaborative platform to lead the revolution of the construction industry, engaging startups, entrepreneurs, universities, and other stakeholders to tackle the challenges in the construction environment and shape the industry’s future. For more information on Cemex Ventures, please visit: www.cemexventures.com.
About BCA
The Building and Construction Authority (BCA) champions a safe, sustainable, and liveable built environment for Singapore. As a leader in the sector, BCA is dedicated to driving industry transformation and setting rigorous standards in building safety, quality, and environmental sustainability. By advancing innovation, digitalisation, and the development of a skilled workforce, BCA fosters a dynamic industry that is ready to meet the evolving needs of the nation and build a resilient and progressive built environment for all. For more information, visit www.bca.gov.sg.
About Caterpillar Ventures
Caterpillar Ventures supports early-stage companies delivering innovative solutions in autonomy, robotics, energy transition, sustainability, and industrial technology. With the backing of Caterpillar Inc., we help founders turn breakthrough ideas into scalable impact across global industries. Visit caterpillar.com.
About Dysruptek
Formed in 2018, Dysruptek is the venture investment arm of The Haskell Company. Dysruptek seeks to invest in disruptive Architecture, Engineering and Construction technologies reshaping the built world. Invest. Invent. Innovate. For more information, please visit: www.dysruptek.com.
About Ferrovial
Ferrovial is one of the world’s leading infrastructure companies, operating in more than 15 countries with over 25,000 employees worldwide. For more information visit: www.ferrovial.com.
About Hilti Venture
Hilti Venture is the CVC arm of Hilti Group, investing globally in technologies transforming how the world is built, combining capital with strategic value and access to real-world jobsites. For more information visit: www.hilti.group.
About VINCI Group’s Leonard
Leonard is VINCI’s innovation and foresight platform, supporting startups and innovative projects in construction, mobility, energy and real estate. For more information visit: www.leonard.vinci.com.
About NOVA by Saint-Gobain
NOVA by Saint-Gobain is the venture capital arm of Saint-Gobain, supporting entrepreneurs advancing sustainability through strategic partnerships and investments. For more information visit: www.nova-saint-gobain.com.
About Trimble
Trimble is a global technology company connecting the physical and digital worlds to transform the way work gets done. For more information visit: www.trimble.com.
About Zacua Ventures
Zacua Ventures is an early-stage venture capital fund investing in Sustainability, Productivity and Urbanization across the built environment, supporting visionary entrepreneurs globally. For more information visit: www.zacuaventures.com.
For decades, construction has moved at the pace of its own certainties: blueprints, timelines, materials, and labor. That equation is changing now, and not as a passing trend. Technology is entering every phase of a project’s life cycle, from the first line drawn in design software to the sensor monitoring a bridge twenty years after it opens, and it’s redefining what it means to build well.
At Cemex Ventures, we’ve spent years watching this shift up close. Not as spectators, but as active investors in the startups driving it. This year, with the Construction Startup Competition 2026 (CSC26), we’ve defined five verticals that together map out the most complete picture yet of where this industry is headed: Preconstruction Tech, Jobsite Productivity & Building Systems, ClimaTech for the Built World, Smart Manufacturing & Logistics, and Smart Buildings & Infrastructure.
Let’s walk through each one. And at the end, we’ll tell you how your startup can be part of this conversation.
Every construction project is largely decided before construction even begins. The precision of a cost estimate, a risk assessment, or a permitting process determines whether a project turns a profit or becomes a financial sinkhole.
That’s why the first CSC26 vertical focuses on Preconstruction Tech: technologies that use data and analytics to improve decision-making before a project breaks ground. This covers BIM and digital twins, cost estimation and budgeting, document management, payment and finance, permitting and compliance, planning and scheduling, risk assessment and scenario planning, site analysis and feasibility, and tendering and bid management.
The shared goal across all of these solutions is clear: reduce uncertainty. The earlier a construction company can anticipate a cost overrun, a delay, or a regulatory risk, the more room it has to course-correct. The startups building in this space aren’t just digitizing old paper-based processes — they’re giving the industry something it never had at this scale: predictive visibility.
Once a project breaks ground, the challenge shifts entirely. It’s no longer about deciding — it’s about executing well, with the right resources, at the right time, without costly mistakes.
The second vertical, Jobsite Productivity & Building Systems, brings together everything that helps a jobsite function as a coordinated system: 3D printing, alternative construction systems, AR/VR for training, equipment tracking, field data capture and reporting, geotechnical analysis, industrialized and automated construction (offsite, modular, precast), jobsite robotics and automation, productivity analytics, progress tracking and site intelligence, project management, quality control and inspection, safety management, and workforce management.
What’s interesting about this vertical is that it tackles one of the industry’s most persistent problems: the productivity gap compared to other sectors. Construction has been slow to adopt automation and real-time data, but the startups competing here are proving that gap can close — one jobsite, one data point at a time.
The built environment is one of the planet’s largest consumers of resources and sources of emissions. But beyond the number you already know, what matters right now is what’s happening on the ground: tightening regulations, net-zero targets with real deadlines, and clients who no longer accept “that’s how it’s always been done” as an answer.
ClimaTech for the Built World brings together the technologies capable of meeting that pressure without sacrificing performance or cost: alternative fuels and new energy sources, carbon tools and calculators, carbon capture, utilization and storage (CCUS), circular construction and waste management, energy efficiency, environmental conservation and mitigation, machinery electrification, SCMs and material enhancers, sustainable materials, sustainable product libraries and life cycle assessment (LCA) tools, and water efficiency and management.
What sets the winning startups in this space apart is that they don’t pitch sustainability as an ethical add-on — they pitch it as a business lever: materials that cost less over time, processes that consume less energy, buildings that depreciate more slowly because they’re built to last and built to comply.
Construction no longer starts or ends at the jobsite. Increasingly, value is created in manufacturing plants, quarries, warehouses, and logistics routes that feed into projects.
That’s where the fourth vertical, Smart Manufacturing & Logistics, comes in: advanced materials, digital twins of industrial assets, energy optimization in industrial processes, fleet management for raw material extraction, industrial IoT, optimization of materials manufacturing (mixes, coatings, binders), optimized control systems, predictive maintenance for heavy equipment, process analytics and AI optimization, quality control and material consistency, quarry and mining operations management, delivery solutions, fleet management and logistics optimization, inventory management, marketplaces for equipment and materials, procurement and supplier management, and warehouse automation.
This vertical connects directly to something we’re already seeing across the Cemex Ventures ecosystem: the line between construction and heavy industry is blurring. Startups that understand both worlds — how things are manufactured and how things get built — hold a major competitive edge.
Finally, the fifth vertical looks beyond handover day. A building or a piece of infrastructure doesn’t end when it opens — it begins an operational life that can last decades, and that life can be optimized too.
Smart Buildings and Infrastructure brings together connected systems, sensors, and data that make it possible to operate and maintain assets more efficiently, safely, and intelligently: asset management, building management systems (BMS), digital twins in the operations phase, energy management systems, facility management platforms, infrastructure monitoring (bridges, roads), performance management, smart cities and connected infrastructure, and smart sensors and IoT integration.
Here, the challenge isn’t building better — it’s operating better what’s already built. And since most of the world’s buildings and infrastructure already exist, the market potential for these solutions is, quite simply, enormous.
If these five verticals prove anything together, it’s that the future of construction won’t be defined by a single disruptive technology, but by the sum of many innovations working across different phases of a project’s life cycle. From the decision to invest in a plot of land to the sensor that flags a crack in a bridge thirty years later, every phase has room to improve — and every improvement compounds with the rest.
That’s exactly the vision behind the Construction Startup Competition, the flagship program from Cemex Ventures and Zacua Ventures to identify, connect with, and invest in the startups building this new industry. Since its first edition, CSC has been a meeting point between founders with real solutions and the industry players — builders, manufacturers, operators, and investors — who need those solutions to stay competitive.
The CSC26 edition arrives with these five updated verticals precisely to reflect where innovation actually lives today: not in silos, but in an interconnected ecosystem where preconstruction, execution, sustainability, manufacturing, and operations all feed into one another.
For a growth-stage startup, joining CSC26 isn’t just a visibility opportunity. It’s direct access to:
It doesn’t matter whether your startup fits neatly into one vertical or crosses several of them, as the most interesting innovation often does. What matters is that you’re solving a real industry problem with technology that already works, or is close to working, at scale.
If your startup operates in any of these five verticals — Preconstruction Tech, Jobsite Productivity & Building Systems, ClimaTech for the Built World, Smart Manufacturing & Logistics, or Smart Buildings & Infrastructure — now is the time to take the step.
Applications for the Construction Startup Competition 2026 close on June 28th.
This deadline isn’t flexible. Selected startups will move directly into an evaluation process with the Cemex Ventures and Zacua Ventures team, and only those who apply on time will get that chance.
Cemex has been named a Global Innovator at the 6th Annual BuiltWorlds Global Innovators Awards. Explore the recognition, context, and Cemex Ventures’ track record of industry-leading innovation in construction technology.
Cemex has once again earned its place among the world’s most forward-thinking organizations in the built environment. At the 6th Annual BuiltWorlds Global Innovators Awards, Cemex was named one of the Global Innovators Top 50— a prestigious list that spotlights fifty companies from around the world driving the digital transformation of construction and infrastructure.
This recognition is more than a badge of honor. It is a reflection of a sustained, deliberate commitment to innovation that Cemex Ventures has been building since its founding in 2017.
BuiltWorlds is one of the leading research and events organizations in the Architecture, Engineering, and Construction (AEC) sector. Each year, it publishes the Global Innovators list to recognize organizations that are actively shaping the future of the built environment through technology adoption, investment, and digital transformation.
Now in its sixth edition, the award has evolved into one of the most respected benchmarks of innovation leadership in the global construction industry. This year’s honorees were selected based on their strategic moves in digitalization, sustainability, and technology deployment across the asset lifecycle, from design and procurement through construction, operations, and maintenance.
As Audrey Lynch, Director of Research at BuiltWorlds, noted about this year’s cohort: the recognized companies represent the very best of the industry’s efforts to improve how we build and operate structures and infrastructure.
Cemex Ventures was launched in 2017 as the open innovation and corporate venture capital (CVC) arm of Cemex. Since then, it has grown into one of the most active investors and innovation catalysts in the global construction technology ecosystem.
With investments in over 25 companies across the AEC space, Cemex Ventures has built a portfolio that directly supports Cemex’s broader “Future in Action” net-zero roadmap. The strategy is clear: back startups that can deliver measurable environmental and operational impact, and integrate those solutions across Cemex’s operations in the Americas and Europe.
The 2026 Global Innovators recognition is part of a growing pattern of external validation for Cemex’s innovation leadership. Here is a timeline of key accolades:
Cemex Ventures was featured in BuiltWorlds’ 5th Annual Global Innovators list, recognized as one of the most active investors and innovators in the built world, with particular mention of its Startup Competition and CVC activities in construction tech and industry 4.0.
Cemex was recognized among the Top 100 Corporate Startup Stars for two consecutive years — 2023 and 2024 — in the annual celebration of best global practices in open innovation, organized by the International Chamber of Commerce (ICC) and Mind the Bridge. In 2023, Cemex additionally received the Special Award: CVC to Deploy Sustainable Construction, acknowledging its outstanding role in fostering corporate-startup collaboration focused on sustainability.
In one of its most significant recognitions to date, Cemex Ventures was named Sustainability Investor of the Year at the BuiltWorlds 2025 Investor Awards. The award was presented to Jesús Ortiz, representing Cemex Ventures, during a ceremony that brought together global leaders in infrastructure and construction technology. The recognition specifically acknowledged the firm’s growing portfolio of startups focused on climate solutions, digitalization, and advanced construction technologies — including its strategic investment in Terra CO2, whose OPUS SCM product can reduce cement-related emissions by up to 70%.
The most recent recognition. Cemex has been named one of the 50 leading global organizations advancing the future of the built environment at the 6th Annual BuiltWorlds Global Innovators Awards.
The construction industry stands at an inflection point. Governments are ramping up investment in transport, energy, and urban infrastructure. At the same time, the sector faces mounting pressure to decarbonize, digitize, and improve productivity, challenges that cannot be solved with yesterday’s tools.
For Cemex Ventures, innovation is not a side initiative. As we firmly believe at Cemex Ventures: innovation is no longer optional for the industry , it is the operating layer behind productivity, sustainability, and scalability across the built world.
Companies that integrate technology effectively are increasingly setting the pace for the rest of the industry. Being recognized on the Global Innovators list is a signal that Cemex is not just adapting to the future of construction — it is helping to define it.
The conversation doesn’t stop here. Cemex will be represented at the upcoming #ParisGlobalSummit hosted by BuiltWorlds, where leaders from across the global construction ecosystem, startups, corporates, investors, and innovators, come together to accelerate the adoption of transformative technologies.
It’s a fitting stage for a company that has spent nearly a decade proving that construction can be smarter, cleaner, and more connected.
Construction Startup Competition 2026 is officially open, marking the 10th edition of one of the construction industry’s leading global platforms for startups advancing innovation across the built environment. This year, Cemex Ventures, Caterpillar, Dysruptek by Haskell, Hilti, Leonard by VINCI Group, NOVA by Saint-Gobain, BCA, Trimble, and Zacua Ventures once again join forces to identify and support the next wave of high-potential startups transforming the way the world builds.
Now in its landmark 10th edition, the Competition continues to connect emerging companies with leading organizations, investors, and industry decision-makers seeking scalable solutions to some of construction’s most pressing challenges. Startups selected for the program will gain access to strategic visibility, valuable industry connections, potential pilot opportunities, and exposure to capital partners across a global innovation ecosystem.
This year’s Construction Startup Competition 10th edition introduces five strategic focus areas aligned with the sector’s evolving priorities: Preconstruction Tech, Jobsite Productivity & Building Systems, ClimaTech for the Built World, Smart Manufacturing & Logistics, and Smart Buildings & Infrastructure. Through these categories, the Competition aims to spotlight the technologies driving greater efficiency, resilience, sustainability, and performance across the construction value chain.
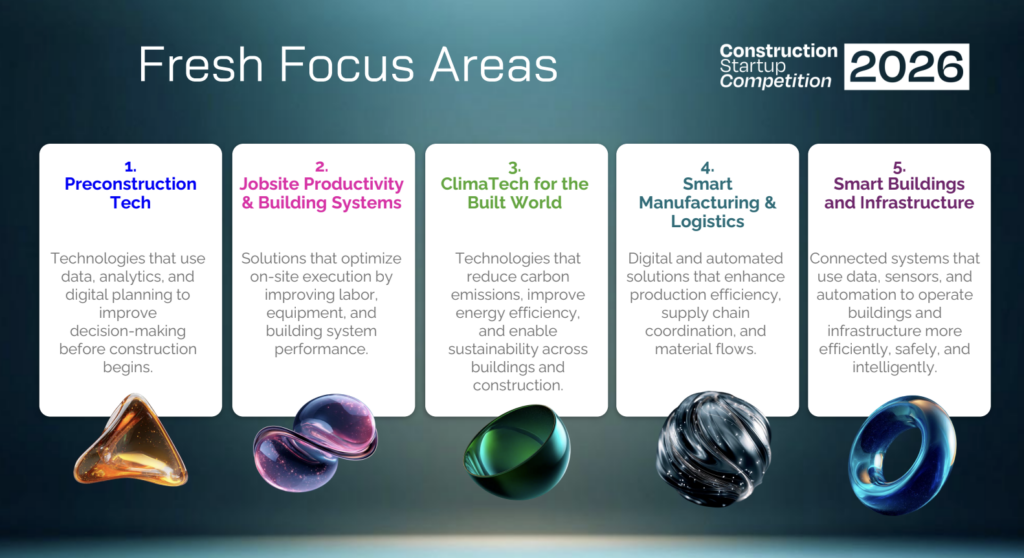
To mark its 10th anniversary, Construction Startup Competition 2026 will conclude with three flagship Pitch Days designed to connect startups with regional innovation hubs and global industry leaders. Finalists will have the opportunity to present their solutions in Singapore, Helsinki, and Las Vegas.
Over the past decade, Construction Startup Competition has become a recognized launchpad for startups seeking to scale internationally, validate their technologies with leading industry players, and unlock new business opportunities. Its strong global network and track record of fostering collaboration between startups, investors, and corporates have positioned the Competition as a key platform for innovation in construction.
“The 10th edition of the Construction Startup Competition reflects both the scale of the opportunity ahead for construction innovation and our continued commitment to the talent shaping its future. For startups, this competition represents far more than visibility; it is a gateway to strategic industry exposure, meaningful connections, and tangible opportunities for growth. At Cemex Ventures, we believe the future of construction will be built by bold entrepreneurs, and this platform is one of the ways we help bring that future closer,” said Jesús Ortiz, Head of Cemex Ventures.
As the construction industry continues to evolve, a new generation of ConTech and Cleantech innovators is being called to redefine how the sector designs, builds, and operates. Startups from around the world are invited to apply and become part of a global platform built to accelerate the solutions shaping the future of construction.
Official Website: https://constructionstartupcompetition.tech/
